Interest and the Time Value of Money
Simple and Compound Interest
Section titled “Simple and Compound Interest”Present and Future Value
Section titled “Present and Future Value”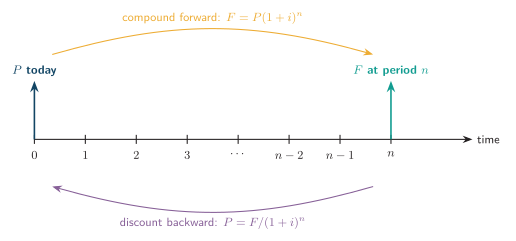
Present and future values as economically equivalent cash flows
| Factor | Formula | Notation |
|---|---|---|
| Future value, single payment | ||
| Present value, single payment | ||
| Future value, uniform series | ||
| Present value, uniform series | ||
| Capital recovery | ||
| Sinking fund |
Standard discrete-compounding factors
The uniform-series factors above describe an ordinary annuity, with equal end-of-period payments. An annuity due has payments one period earlier, so the ordinary-annuity value is multiplied by .